PVCNN-Transformer Model for Virtual Power Plant Bidding Using Renewable Output and Market Price Sequences
Authors
Dario Filipović, Edin Radoš, Krešimir ĆosićFiles
Key Information
Journal
Published in Vol. 4 No. 1 (2024) of Journal of Smart Operations and Management Engineering.
Journal of Smart Operations and Management Engineering (JSOME) eISSN: 3136-7666 is an international, peer-reviewed forum dedicated to publishing cutting-edge research at the intersection of process systems engineering, advanced operations research, and intelligent management. The journal bridges the gap between technical system design and executive decision-making, focusing on how data-driven algorithms, automation frameworks, and intelligent computing transform modern industrial operations.
JSOME welcomes original research articles, rigorous reviews, and methodological contributions addressing complex industrial systems, supply chain networks, energy systems, and process industries.
About the JournalAbstract
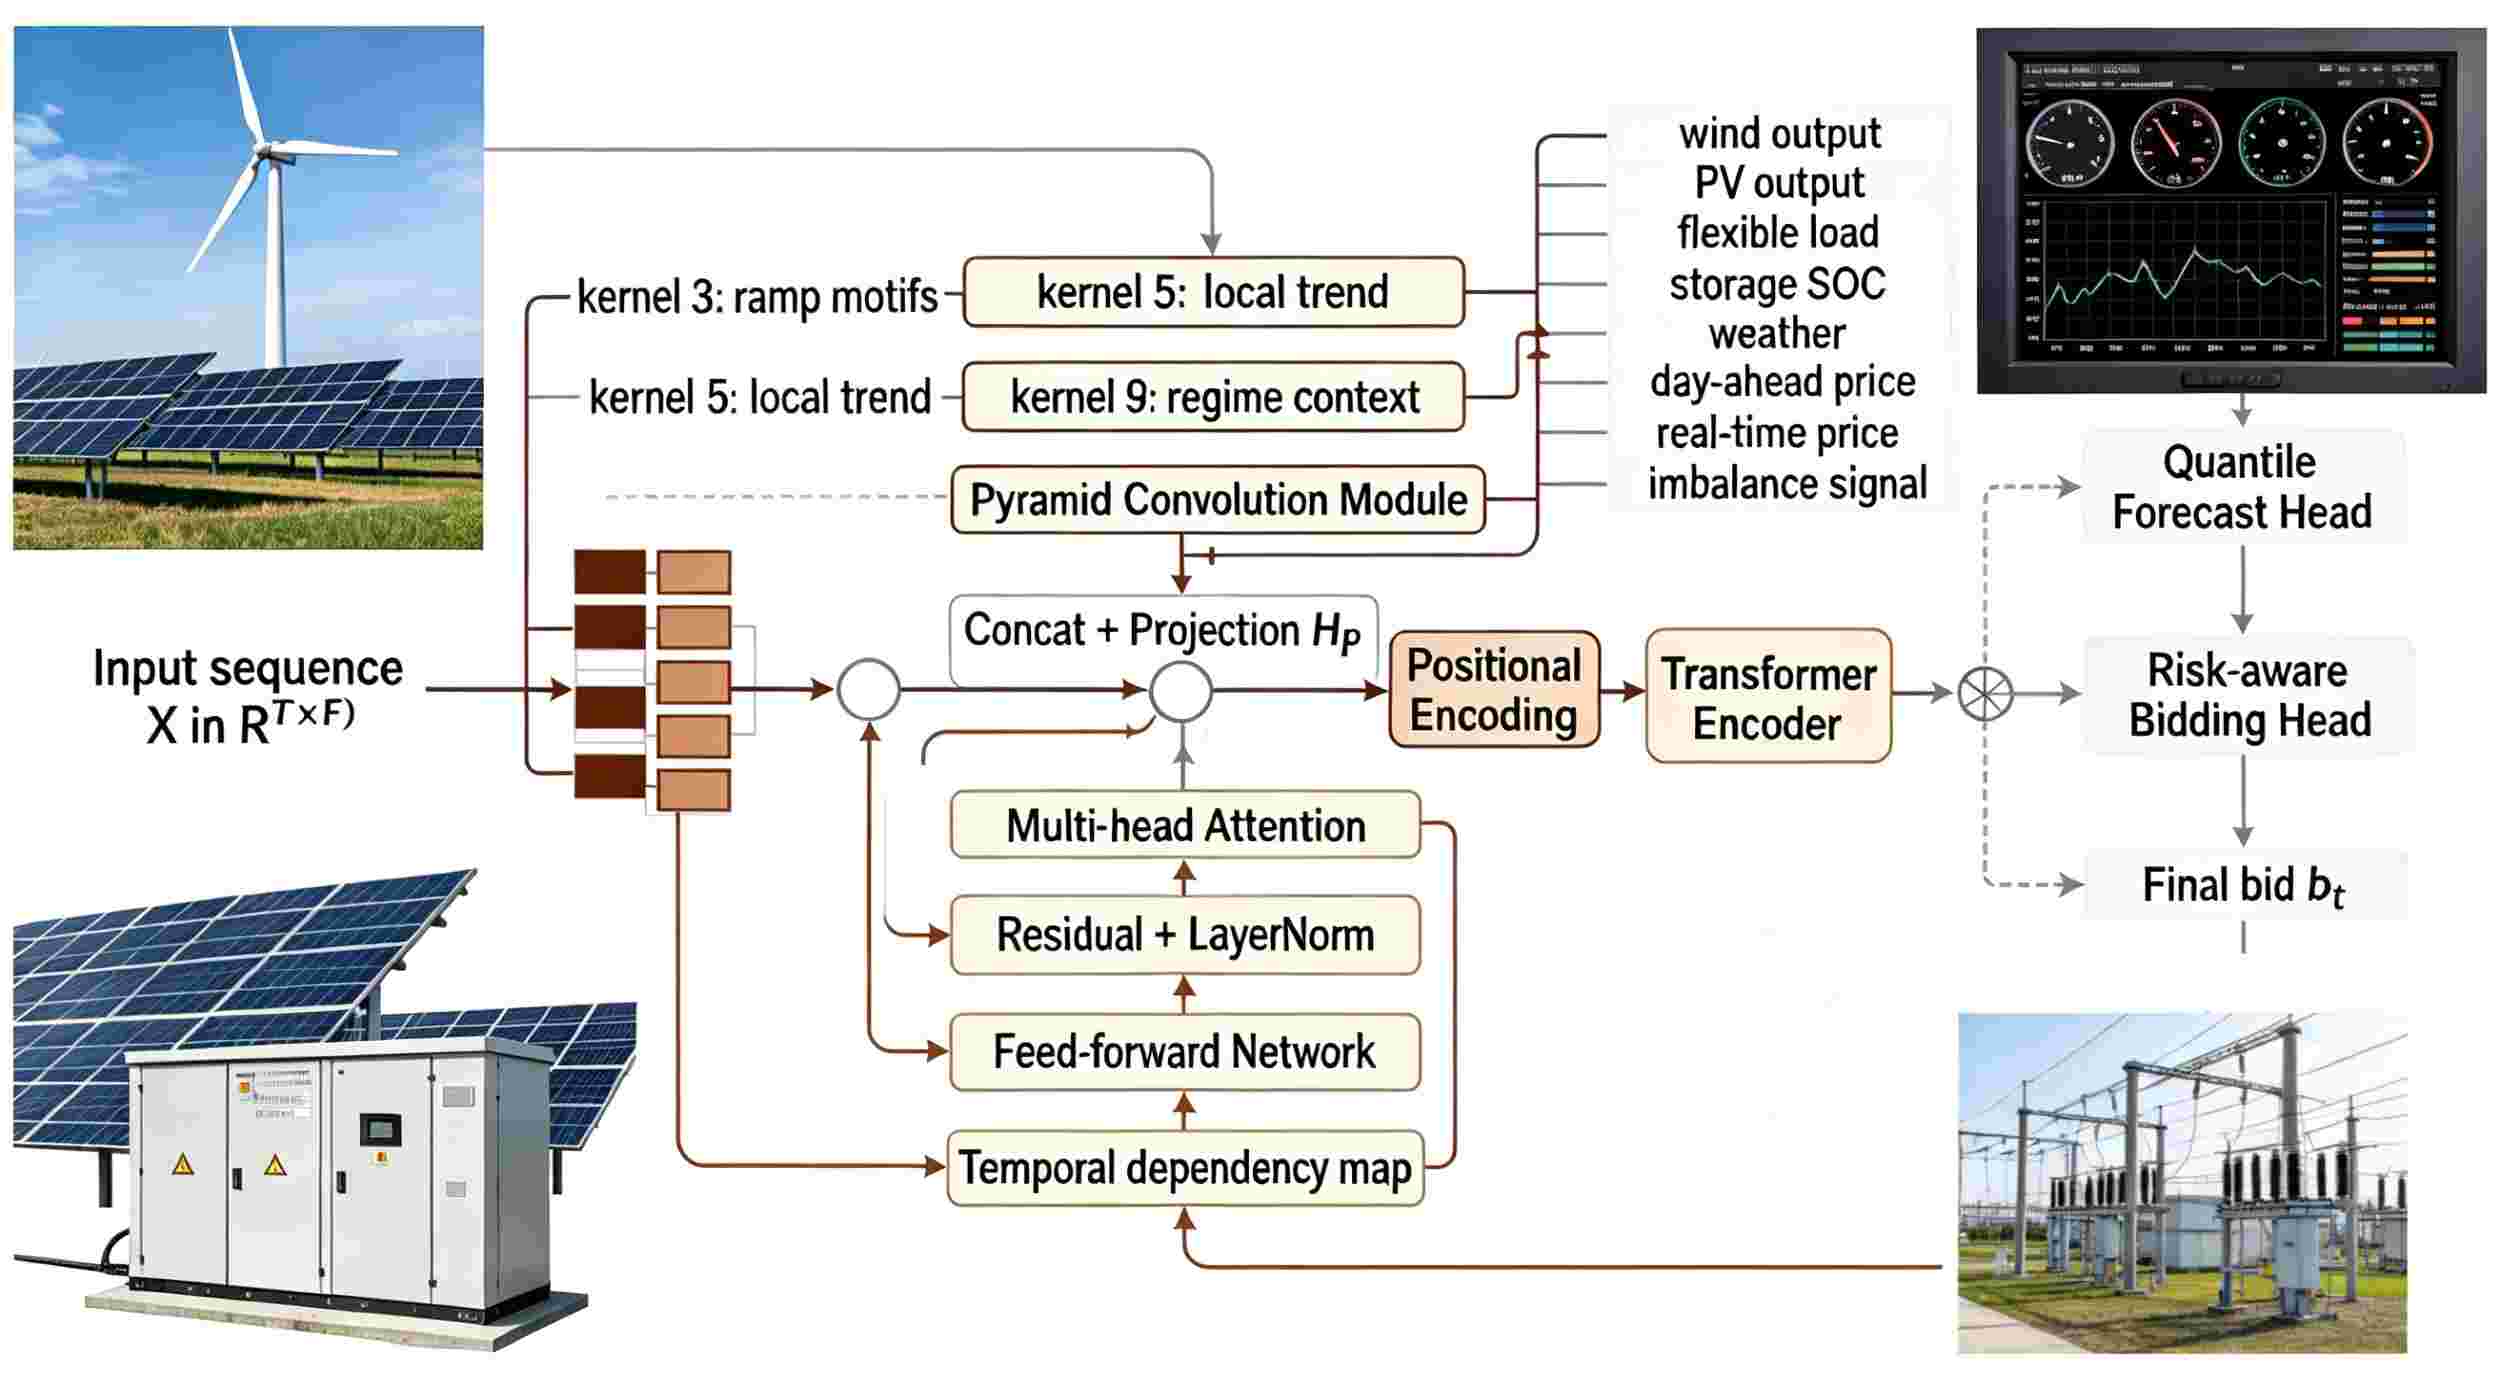
Virtual power plants are becoming active market participants, yet their bidding decisions remain highly exposed to coupled renewable-output uncertainty and nonstationary electricity-price sequences. This paper proposes a PVCNN-Transformer model for day-ahead virtual power plant bidding, in which pyramid convolutional branches extract local wind, photovoltaic and price-ramp patterns, Transformer self-attention represents longer temporal dependence across 96 dispatch intervals, and an imbalance-aware layer converts probabilistic forecasts into executable bid curves. The model is evaluated through chronological market replay on 365 daily profiles containing wind power, photovoltaic output, flexible load, storage state, day-ahead price, intraday price and imbalance settlement signals. Compared with persistence, LSTM, temporal convolutional network and vanilla Transformer benchmarks, the proposed method reduces renewable-output forecasting error by 18.7%, lowers price forecasting error by 15.4%, raises mean daily profit from 18.92 kUSD to 21.46 kUSD, and decreases imbalance penalties by 23.8%. The median profit reaches 21.71 kUSD/day, while the interquartile range is narrowed to 3.84 kUSD/day. Ablation results show that pyramid convolution contributes 0.61 kUSD/day, attention encoding contributes 0.72 kUSD/day, and the risk-aware bidding layer contributes 0.84 kUSD/day. These results indicate that joint temporal representation and market-risk conversion improve both profitability and operational robustness for virtual power plant bidding under renewable and price volatility.